Key takeaways
- Varidi’s “0% interest” is accurate. The payments carry no interest.[1]
- The cost is a one-time setup fee: typically 2% to 18% per Varidi,[2] and 18% to 22% on guaranteed plans in a 2025 study.[3]
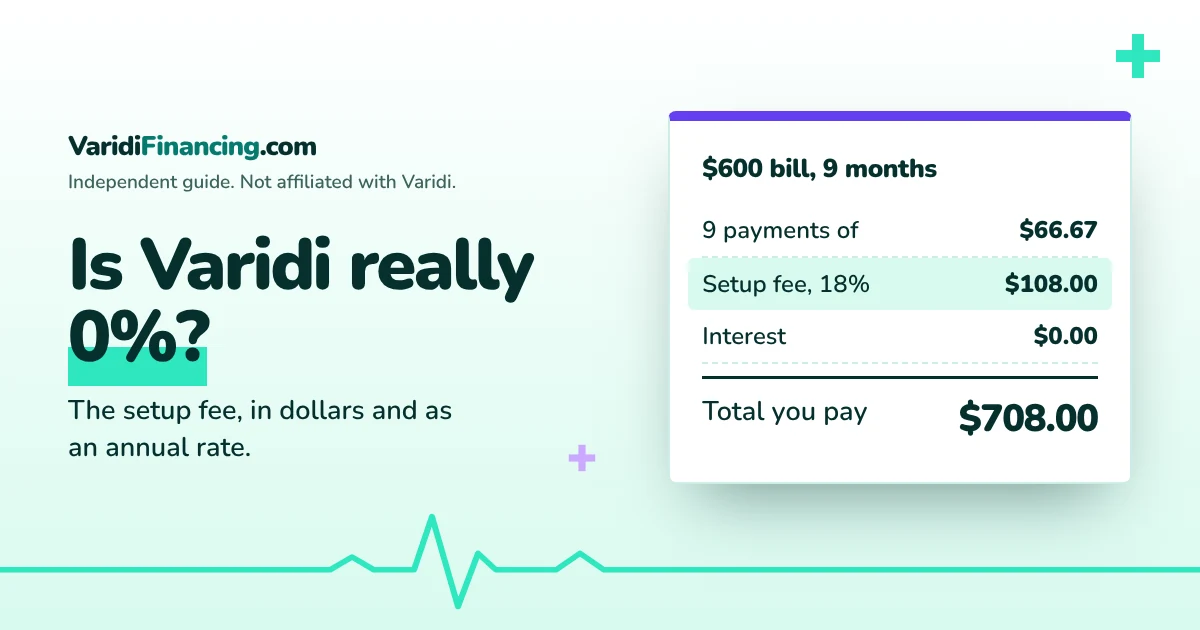
- On a $600 bill over 9 months, that is between $12.00 and $132.00.
- Spread over a short plan, an 18% fee costs about as much as a loan at 50% APR.
“Zero percent” is the phrase that gets people to say yes at the front desk. With Varidi it is true, and it is also not the whole price. This article puts numbers on the part that the headline leaves out, so you can decide with the same information the provider has.
What “0% interest” means on a Varidi plan
A Varidi plan divides your bill into equal monthly payments. Nothing is added to those payments. Varidi’s pricing page calls them principal-only.[4] There is no rate that can jump, and no deferred interest waiting at the end of a promotional period.
That is a real advantage. The Consumer Financial Protection Bureau found that patients paid about $1 billion in deferred interest on medical credit cards and loans between 2018 and 2020.[5] A Varidi plan cannot do that to you.
The setup fee: what Varidi says, and what a study recorded
Varidi collects a setup fee before your plan starts. Three published descriptions exist, and they do not line up perfectly:
- Varidi’s consumer FAQ: typically 2% to 18% of the contract amount, depending on your profile and the number of monthly payments.[2]
- Varidi’s pricing page: a small one-time fee “based on client affordability,” with no figure.[4]
- The 2025 Frontiers study: a one-time fee of 18% to 22% on the guaranteed plan, and 5% upfront on the true payment plan.[3]
In that study, 94.6% of the 424 accounts were guaranteed plans.[3] So among the clients researchers actually tracked, the higher fee was the normal one. Plan for the upper end and be pleased if you are quoted less.
The fee in dollars
The study’s average treatment cost was $623.77 and the average term was 9 months.[3] We use a round $600 over 9 months.
Swipe the table sideways to see every column.
| Setup fee | Due at the start | 9 payments of | Total you pay |
|---|---|---|---|
| 2% | $12.00 | $66.67 | $612.00 |
| 5% | $30.00 | $66.67 | $630.00 |
| 10% | $60.00 | $66.67 | $660.00 |
| 18% | $108.00 | $66.67 | $708.00 |
| 22% | $132.00 | $66.67 | $732.00 |
Notice what the fee does to your first day. At 18%, you need $108.00 in hand before treatment starts. If you are asking for a payment plan because money is tight this week, that upfront amount is the real hurdle.
Turning a flat fee into an annual rate
A fee of 18% sounds lower than a credit card at 33%. The two numbers are not measuring the same thing. A card’s APR is a yearly rate charged on a balance that shrinks as you pay. A setup fee is charged once, in full, on the starting balance, and you repay within months.
To compare them fairly, we ask: what loan APR would cost exactly the same? We treat the fee as a prepaid charge, so you effectively receive the bill amount minus the fee and repay the full bill in equal installments. Then we solve for the rate.
Swipe the table sideways to see every column.
| Setup fee | 6 months | 9 months | 12 months | 18 months |
|---|---|---|---|---|
| 2% fee ($12) | 7% | 5% | 4% | 3% |
| 5% fee ($30) | 18% | 12% | 10% | 7% |
| 10% fee ($60) | 37% | 26% | 20% | 14% |
| 18% fee ($108) | 72% | 50% | 38% | 26% |
| 22% fee ($132) | 91% | 63% | 49% | 33% |
Two patterns stand out. A small fee stays cheap on any term. And for the same fee, a shorter plan means a higher equivalent rate, because you are paying the same dollars to borrow for less time.
How that stacks up against the alternatives
- A credit card at 32.99% APR. $600 repaid in 9 equal payments costs about $85.45 in interest.[6] That is less than an 18% setup fee ($108.00) and more than a 10% fee ($60.00).
- A point-of-sale plan at the top of its range. Cherry and Sunbit list APRs up to 35.99%.[7][8] At that rate the same $600 over 9 months costs about $93.52.
- A true 0% plan. If you qualify for one with no fee, it costs nothing extra. Nothing beats that.
The honest summary: at a low fee Varidi is the cheapest realistic option for someone with damaged credit. At a high fee it is one of the more expensive ones, and you are paying for access and certainty.
Want a number to compare your Varidi quote against? Request personal loan offers and look at the APR.
Compare financing optionsWhat the fee buys you
It is fair to ask why anyone would pay 18%. On a guaranteed plan, Varidi promises the provider its money on schedule even if you stop paying, so Varidi carries the default risk.[3][9] It does this without checking credit.[9] The fee is the price of that risk.
For the client, the fee buys three things: approval that does not depend on a credit score, no inquiry on your file and a total that is fixed on day one. In the study, 39.9% of applicants who gave a reason had already been declined or under-approved elsewhere.[3] For them, the comparison was not Varidi against a cheaper loan. It was Varidi against no treatment.
Five ways to pay less
- Ask which plan type you are being offered. The true payment plan cost clients 5% upfront in the study, against 18% to 22% for the guaranteed plan.[3] Not every provider offers both.
- Ask how the term changes the fee. Varidi says the fee depends partly on the number of payments.[2] Have the staff quote two terms.
- Finance less. A percentage fee shrinks with the balance. Pay what you can today and put only the rest on the plan.
- Check one alternative first. A soft-check prequalification with another plan, where available, costs you nothing and may show a 0% offer.
- Get the fee in dollars before you tap “accept.” Percentages hide in small print. Dollars do not.
So, is Varidi really 0%?
Yes on interest. No on cost. Varidi is transparent that a fee exists, and less transparent about how much it will be until you apply. Used with open eyes, by someone who needs approval without a credit check, it does what it says. Just do the arithmetic first. Our payment estimator takes ten seconds.
Frequently asked questions
Does Varidi charge interest?
Is the Varidi setup fee refundable?
Varidi’s public pages do not say. Ask your provider and get the answer in writing before you pay, especially if your treatment plan could change.
Why would two people be charged different setup fees?
Is a setup fee the same as APR?
No. APR is a legal disclosure for credit. A Varidi plan is not a loan and has no APR. We convert the fee to an equivalent annual rate only so you can compare it with loan and card offers on equal terms.
More guides
- Varidi vs. CareCredit: which is safer for a vet or dental bill?
- How to pay a vet bill you can’t afford: 8 options, ranked by cost and risk
- No-credit-check dental payment plans: how they work and what they cost
- Varidi vs. Scratchpay: which vet payment plan costs less?
- Varidi requirements: who qualifies and what you need to apply
- Varidi vs. Cherry vs. Sunbit: which payment plan costs less?
- Missed a Varidi payment? What happens and what to do
- Varidi financing: the complete overview
Sources (10)
- Varidi, “For Customers”. Accessed November 13, 2026.
- Varidi, “Individual Frequently Asked Questions”. Accessed November 13, 2026.
- Cammisa H.J., Hill S. (2025). “A prospective observational study of how veterinary clinics and their clients utilized a no-credit-check, third-party managed installment financing option to increase access to veterinary care.” Frontiers in Veterinary Science, vol. 12. Accessed November 13, 2026.
- Varidi, “Pricing”. Accessed November 12, 2026.
- Consumer Financial Protection Bureau, “CFPB Report Highlights Costly Credit Cards and Loans Pushed on Patients” (May 4, 2023). Accessed November 12, 2026.
- NerdWallet, “CareCredit Rewards Mastercard Review” (June 17, 2026). Accessed November 12, 2026.
- Cherry, “Does Cherry Charge Deferred Interest?”. Accessed November 13, 2026.
- Sunbit, “Dental Financing”. Accessed November 13, 2026.
- Varidi, “Services”. Accessed November 13, 2026.
- Varidi, “How It Works”. Accessed November 12, 2026.