The quick answer
- Choose Varidi if you have been declined for credit, want no inquiry or are not certain you can clear a balance by a deadline.
- Choose CareCredit if you are approved and completely sure you will pay the full balance inside the promotional period.
- The risk is different in kind. Varidi’s cost is fixed on day one. CareCredit’s can be zero or several hundred dollars, depending on one deadline.
Your vet or dentist has just handed you an estimate, and there are two logos on the counter. One is a credit card. The other is a payment plan. They solve the same problem in opposite ways, and the cheaper one depends almost entirely on how the next twelve months of your budget go.
How each one works
Varidi
Varidi is payment plan software your provider uses to split one bill into equal monthly payments. There is no interest and no credit check. You pay a one-time setup fee before the plan starts, typically 2% to 18% of the amount according to Varidi, and 18% to 22% on guaranteed plans in a 2025 study.[1][2][3] Varidi is not a lender.[1]
CareCredit
CareCredit is a credit card issued by Synchrony Bank, accepted across a network of dentists, eye doctors, hospitals and veterinary practices. NerdWallet lists its ongoing APR at 32.99%, with a 39.99% penalty APR after a late payment.[4] On purchases of $200 or more it offers promotional periods of 6, 12, 18 or 24 months with deferred interest. For bigger bills there are fixed-payment plans over 24 to 60 months at a reduced APR, 17.90% to 19.90% in NerdWallet’s June 2026 example.[4]
Side by side
Swipe the table sideways to see every column.
| Varidi | CareCredit | |
|---|---|---|
| What it is | Provider payment plan[1] | Credit card from Synchrony Bank[4] |
| Credit check | None[5] | Credit card application |
| Interest | 0%[1] | Deferred-interest promos, then 32.99% APR[4] |
| Upfront cost | One-time setup fee[2] | None |
| Worst case | You pay the fee and the bill | Back-dated interest on the full purchase, plus a 39.99% penalty APR after a late payment[4] |
| Reports to credit bureaus | No[2] | Yes, as a credit card |
| Where you can use it | Participating providers[1] | CareCredit network[4] |
One bill, three outcomes
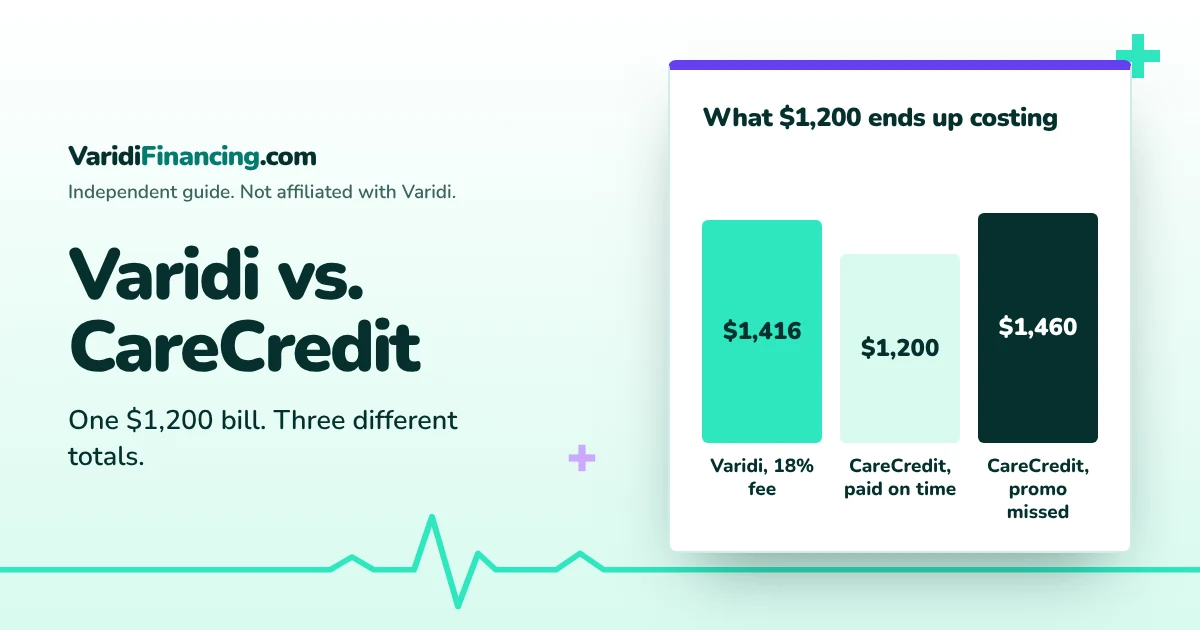
Take a $1,200 dental bill and twelve months to pay it. These are our calculations from the published terms.
Outcome 1: Varidi
Twelve payments of $100.00. With a 10% setup fee you pay $120.00 at the start, $1,320.00 in total. With an 18% fee you pay $216.00 at the start, $1,416.00 in total. Whatever happens next, that total does not change.
Outcome 2: CareCredit, promotion paid off in time
You put $1,200 on a 12-month promotion and pay $100 a month without fail. Total cost: $1,200. No fee and no interest. This is the cheapest result on the page, and it is why CareCredit is popular.
Outcome 3: CareCredit, promotion missed
Life happens and you pay $75 a month instead of $100. At month twelve you have paid $900 and still owe $300. Because the interest was deferred and not waived, roughly $260 of interest from the past year is added to your account on top of the $300.[4] You are now further behind than the person who paid Varidi’s 18% fee, and the balance is still growing at 32.99%.
For reference, simply financing $1,200 at 32.99% and paying it off over twelve months would cost about $225 in interest.
The real difference is the shape of the risk
Varidi charges you a known amount for certainty. CareCredit charges you nothing if you are disciplined and lucky, and a lot if you are not. The CFPB reported that patients paid about $1 billion in deferred interest on medical credit cards and loans between 2018 and 2020, and that these products typically carry higher rates than ordinary cards.[6]
Be honest about which kind of year you are having. If a surprise car repair would knock you off schedule, the deferred-interest promotion is a bet you can lose.
Neither option fits? See what a fixed-rate personal loan would cost for the same bill.
Compare financing optionsApproval and access
Varidi says it uses no credit scores, reports or bureaus, and bases eligibility on your ability to make the payments.[5][1] In the 2025 study, 39.9% of applicants who gave a reason said another financing option had declined them or approved too little.[3]
CareCredit approval depends on your credit. If you are declined, the application may still leave an inquiry on your report. If you are approved, you get a reusable line that works at many providers, which Varidi does not offer.
What about bigger bills and longer terms?
Deferred-interest promotions are only part of CareCredit. For larger amounts it also offers fixed monthly payments over 24 to 60 months at a reduced APR. NerdWallet’s June 2026 example for a $1,000 bill shows 17.90% to 19.90%, depending on the term.[4] These plans charge interest from the start, but nothing is back-dated.
Here is a $2,400 bill over 24 months. At 17.90% APR, the payment is about $119.70 and total interest is about $473. A Varidi plan for the same amount, if your provider offers a term that long, would cost $240 at a 10% setup fee or $432 at 18%, with payments of $100.00.
On long terms the two land close together, and three practical points decide it:
- Cash on day one. Varidi’s fee is due before treatment. The CareCredit plan needs nothing upfront.
- Size limits. In the 2025 study, guaranteed Varidi plans covered up to $4,000.[3] A bigger bill may need a different product.
- Paying early. Clearing a CareCredit fixed plan early saves the remaining interest. Clearing a Varidi plan early saves nothing, because the fee is already paid.[2]
Five questions to ask at the counter
- “Do you offer both, and can I see the terms for each before I choose?”
- “For Varidi, what is my setup fee in dollars?”
- “For CareCredit, is this promotion deferred interest or a reduced-APR fixed plan?”
- “What exact monthly payment clears the promotion one month early?”
- “Is there a discount if I pay part of the bill today?”
Write the answers down. Staff are helpful, but they are not the ones who will be making the payments in month eleven.
Which should you choose?
- Pick Varidi when your credit is thin or damaged, you want no inquiry, the bill is modest and you value a total that cannot grow.
- Pick CareCredit when you are already approved or have good credit, and you can set up automatic payments large enough to clear the balance a month before the promotion ends.
- Pick neither when you qualify for a true 0% plan with no fee, or a personal loan at a rate below the equivalent cost of Varidi’s fee. Our alternatives comparison covers both.
Whichever you choose, ask the provider one more question first: is there a discount for paying part of the bill today? A smaller balance makes every option cheaper.
Frequently asked questions
Is Varidi better than CareCredit for bad credit?
Usually, yes. Varidi runs no credit check,[5] while CareCredit is a credit card that requires approval. If you cannot get approved for CareCredit, Varidi may be the option actually available to you.
Does CareCredit really charge 0% interest?
Its short-term promotions charge no interest only if you pay the full promotional balance by the deadline. If you do not, interest is charged from the purchase date on the full original amount.[4] That is deferred interest, not a true 0% rate.
Can I use both Varidi and CareCredit?
If your provider accepts both, you could split a bill, for example putting part on a CareCredit promotion you are sure you can clear and the rest on a Varidi plan. Ask the provider. Each has its own costs.
Which one helps my credit score?
CareCredit is a credit card, so the account and your payments appear on your credit reports. Varidi says it does not report on-time payments.[2] Only CareCredit can build credit, and only CareCredit can damage it through an inquiry or a late payment.
More guides
- Is Varidi really 0%? The setup fee, explained with real numbers
- How to pay a vet bill you can’t afford: 8 options, ranked by cost and risk
- No-credit-check dental payment plans: how they work and what they cost
- Varidi vs. Scratchpay: which vet payment plan costs less?
- Varidi requirements: who qualifies and what you need to apply
- Varidi vs. Cherry vs. Sunbit: which payment plan costs less?
- Missed a Varidi payment? What happens and what to do
- Varidi financing: the complete overview
Sources (6)
- Varidi, “For Customers”. Accessed November 13, 2026.
- Varidi, “Individual Frequently Asked Questions”. Accessed November 13, 2026.
- Cammisa H.J., Hill S. (2025). “A prospective observational study of how veterinary clinics and their clients utilized a no-credit-check, third-party managed installment financing option to increase access to veterinary care.” Frontiers in Veterinary Science, vol. 12. Accessed November 13, 2026.
- NerdWallet, “CareCredit Rewards Mastercard Review” (June 17, 2026). Accessed November 12, 2026.
- Varidi, “Services”. Accessed November 13, 2026.
- Consumer Financial Protection Bureau, “CFPB Report Highlights Costly Credit Cards and Loans Pushed on Patients” (May 4, 2023). Accessed November 12, 2026.