The quick answer
- Choose Varidi if your credit is thin or damaged, you have been declined elsewhere or you do not want anyone looking at your credit.
- Choose Scratchpay if your credit can earn a low APR, if you can clear the bill within six months or if the bill is bigger than a Varidi plan covers.
- The core difference: Varidi charges a one-time setup fee and no interest. Scratchpay charges interest and no setup fee. The fee is fixed on day one. The rate depends on your credit.
Your vet has handed you an estimate, and the front desk mentions two ways to pay it over time. Varidi and Scratchpay were both built for this moment. Humane World for Animals lists Varidi among plans with no credit check at all, and Scratchpay among plans that use only a soft credit check.[1] They price the same bill in opposite ways, so the cheaper one depends on your credit and on how fast you can pay.
How each one works
Varidi: a no-interest plan with a setup fee
Varidi is payment plan software that a clinic uses to split one bill into equal monthly payments. The company says it is not a bank or a lender.[2] There is no interest and no credit check.[2][3] You pay a one-time setup fee before the plan starts: typically 2% to 18% of the amount according to Varidi’s FAQ,[4] and 18% to 22% on guaranteed plans in a 2025 peer-reviewed study.[5] In that study the average plan was $623.77, repaid at $64.74 a month over 9 months.[5]
Scratchpay: a loan with an APR
Scratchpay offers closed-end loans with 12, 18 or 24 monthly payments, for amounts from $200 to $10,000. The APR runs from 0% to 36%, and the lowest rates go to borrowers with exceptional credit profiles. Loans in the U.S. are issued by WebBank. Scratchpay pays the veterinarian directly at the time of care, and you repay Scratchpay.[6]
Three more details matter. To obtain financing, Scratchpay requires a $15 down payment. Checking your eligibility does not affect your credit score, but once you accept a loan your repayment activity may be reported to the credit bureaus. And plans may not be available in every state.[6]
Side by side
Swipe the table sideways to see every column.
| Varidi | Scratchpay | |
|---|---|---|
| What it is | Payment plan run through the clinic. Not a loan.[2] | Closed-end loan issued by WebBank[6] |
| Credit check | None[3] | Plans are based on your credit profile. Checking eligibility does not affect your score.[6] |
| Interest | 0% on every plan[2] | 0% to 36% APR[6] |
| Upfront cost | One-time setup fee, typically 2% to 18%[4] | $15 down payment[6] |
| Amounts | Set by the clinic. Guaranteed plans covered up to $4,000 in the 2025 study.[5] | $200 to $10,000[6] |
| Terms | Set by the clinic. At least 6 months, and 9 on average, in the study.[5] | 12, 18 or 24 months[6] |
| Reports to credit bureaus | No[4] | Repayment may be reported[6] |
| Late payments | No late-fee amount published. Varidi handles follow-up on guaranteed plans.[3] | Late fees apply[6] |
| Where you can use it | Participating providers only[2] | Participating providers. May not be available in all states.[6] |
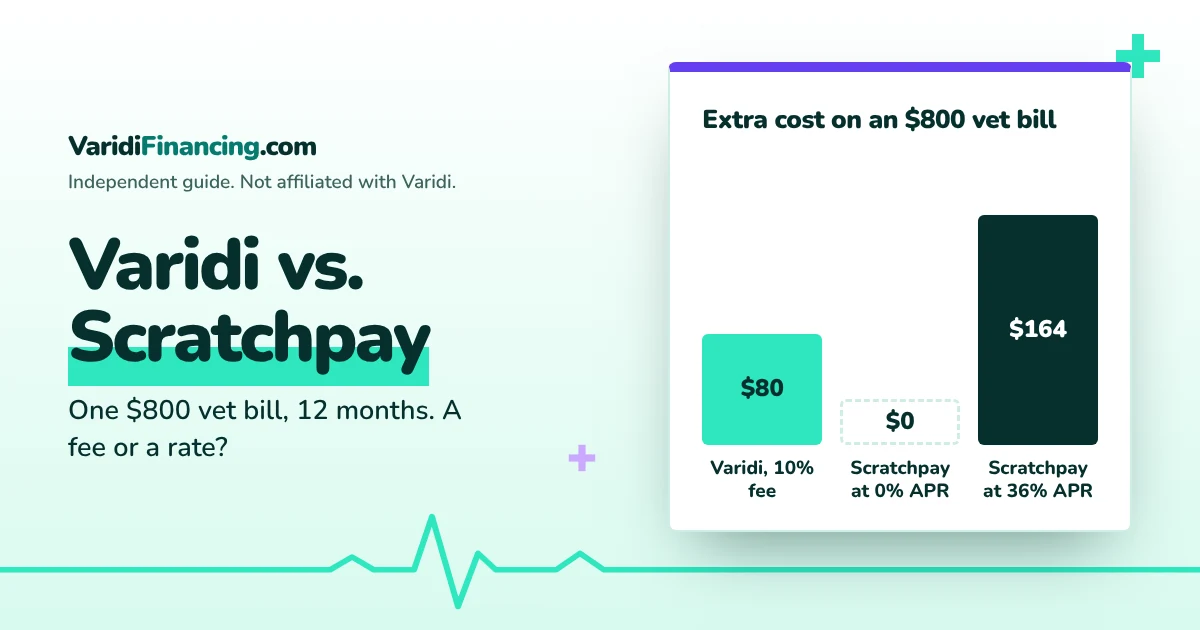
Varidi vs. Scratchpay cost: one $800 vet bill over 12 months
Here is the same bill priced both ways. We used 12 months because it is Scratchpay’s shortest term,[6] and on Varidi the clinic sets the term.[5]
Swipe the table sideways to see every column.
| Option | Due upfront | Monthly payment | Extra cost | Total you pay |
|---|---|---|---|---|
| Varidi, 5% setup fee | $40.00 | $66.67 | $40.00 | $840.00 |
| Varidi, 10% setup fee | $80.00 | $66.67 | $80.00 | $880.00 |
| Varidi, 18% setup fee | $144.00 | $66.67 | $144.00 | $944.00 |
| Varidi, 22% setup fee | $176.00 | $66.67 | $176.00 | $976.00 |
| Scratchpay at 0% APR | $15.00 | $66.67 | $0.00 | $800.00 |
| Scratchpay at 11.99% APR | $15.00 | $71.08 | $52.90 | $852.90 |
| Scratchpay at 19.99% APR | $15.00 | $74.10 | $89.25 | $889.25 |
| Scratchpay at 36% APR | $15.00 | $80.37 | $164.44 | $964.44 |
Three things stand out.
- With strong credit, Scratchpay wins. At 0% APR it adds nothing to the bill, and no Varidi fee can match that.
- In the middle, it is close. A 10% Varidi fee costs $80.00. Scratchpay at 19.99% APR costs $89.25. Scratchpay beats that 10% fee only when your rate is below about 18% APR.
- With weak credit, Varidi often wins. An 18% Varidi fee costs $144.00, which is less than Scratchpay at its 36% maximum ($164.44). At 22% ($176.00), Varidi costs more than any Scratchpay rate on a 12-month plan. That comparison only matters if Scratchpay approves you in the first place.
The totals hide one more difference. Varidi’s fee is due before treatment starts.[4] Scratchpay’s interest is spread across the payments. If cash is tight this week, $144.00 upfront can be harder to find than $80.37 a month.
The fee that matches each Scratchpay rate
To compare a fee with a rate, ask one question: at what APR would the loan’s total interest equal the fee? The table answers it for Scratchpay’s three terms. It works for any bill size, because both costs grow in step with the amount.
Swipe the table sideways to see every column.
| If Varidi quotes you | 12 months | 18 months | 24 months |
|---|---|---|---|
| 5% Varidi setup fee | 9% APR | 6% APR | 5% APR |
| 10% Varidi setup fee | 18% APR | 12% APR | 9% APR |
| 18% Varidi setup fee | 32% APR | 22% APR | 16% APR |
| 22% Varidi setup fee | 38% APR | 26% APR | 20% APR |
To use it, find your Varidi fee in the left column and your term across the top. If the APR Scratchpay offers you is lower than the number in the table, Scratchpay costs fewer dollars. If it is higher, Varidi does. A 10% Varidi fee on an 18-month plan, for example, matches a Scratchpay loan at about 12% APR.
Keep one caution in mind. In the 2025 study the average Varidi plan ran 9 months, and the clinic set the term.[5] A Varidi plan as long as 18 or 24 months may not be on offer at your clinic.
Clinic offers neither Varidi nor Scratchpay? A personal loan can be used at any vet.
Compare financing optionsScratchpay’s Interest Waived Offer vs. Varidi’s 0% interest
Both companies talk about paying no interest, and they mean different things.
Varidi: every plan is interest-free, whatever your credit and however long you take.[2] You always pay the setup fee.[4]
Scratchpay: its Interest Waived Offer credits the interest back if you pay the full balance within the first six months, make every payment on time and tell Scratch you want the offer. The footnote limits it to eligible 12- or 18-month loans, and Scratchpay’s FAQ describes it as an offer for eligible borrowers who set up autopay.[6]
On an $800 bill, clearing the balance in six months means about $133.33 a month, twice the $66.67 that a 12-month plan asks for. If you can manage that and you qualify, Scratchpay can cost you nothing in interest. If you cannot, the interest stays.
Approval: who qualifies for each
Varidi says it runs no credit check and bases eligibility on your ability to make the payments.[3][2] In the 2025 study, the monthly payment could not exceed 10% of the applicant’s self-reported income. Of the applicants who gave a reason for applying, 39.9% had been declined or approved for too little by another option.[5] Our Varidi requirements guide has the full list.
Scratchpay’s plans are personalized from your credit profile, so you see only the plans you are approved for, and every plan is subject to eligibility.[6] Approval is not guaranteed, and the rate you are shown can be anywhere from 0% to 36%.
Credit score: what each one does to your report
- Applying. Varidi says it never performs hard credit checks.[2] Scratchpay says checking eligibility does not affect your score.[6]
- Paying. Varidi says it does not report on-time payments to the credit bureaus.[4] Scratchpay says repayment activity may be reported.[6]
- What that means. A Scratchpay loan paid on time can help your credit history, and one paid late can hurt it. A Varidi plan does neither.
If you fall behind on payments
Scratchpay says late fees apply, and that late or partial payments may bring fees, higher interest charges and a changed repayment schedule. The page we checked does not list the fee amounts.[6]
Varidi’s consumer pages do not publish a late-fee amount, and the 2025 study describes the guaranteed plan as having no interest or penalties.[5] Varidi does say it handles follow-up and collections directly with customers on guaranteed plans.[3] With either company, call before a payment fails, and read the missed-payment terms before you sign.
For clinics
If you run a veterinary practice, the two also work differently on your side of the counter.
- When you are paid. Scratchpay says it pays the veterinarian directly at the time of care.[6] On Varidi’s guaranteed plans the practice is paid in monthly deposits that begin within 48 hours of the transaction and continue even if the client stops paying.[3]
- What it costs you. Scratchpay lists flat pricing of a 5% provider fee for all veterinary practices, with no setup cost.[7] Varidi describes a flat fee per payment with no monthly subscription,[3] and clinics in the 2025 study paid a 5% merchant fee.[5]
- Who you can say yes to. Scratchpay approves clients on their credit profile.[6] Varidi uses no credit check,[3] so it can cover clients a lender would decline.
The two do not have to compete for the same client. A practice can offer a lender for clients with good credit and a no-credit-check plan for everyone else.
Which should you choose: Varidi or Scratchpay?
- Pick Varidi when your credit is thin or damaged, you have been declined elsewhere, the bill is modest and you want a total that cannot grow.
- Pick Scratchpay when you expect a low APR, you can pay the bill off within six months and qualify for the Interest Waived Offer, or you want on-time payments to count toward your credit history.
- Pick Scratchpay for a large bill. Guaranteed Varidi plans in the 2025 study covered up to $4,000,[5] and Scratchpay lends up to $10,000.[6]
- Check both when your clinic offers both. Looking at your Scratchpay rate does not affect your score, so see the rate first. Then ask for the Varidi fee in dollars and use the table above.
If your clinic offers neither, you still have options. Our comparison of Varidi alternatives covers CareCredit, Cherry and Sunbit, our guide to paying a vet bill you can’t afford ranks eight routes by cost, and you can request personal loan offers through the form on this site.
Five questions to ask your vet
- “Do you offer Varidi, Scratchpay or both?”
- “What is my Varidi setup fee in dollars, and over how many months?”
- “Can I check my Scratchpay rate before I decide?”
- “What is due today with each one?”
- “What happens with each one if a payment is late?”
Write the answers down. The cheaper plan is the one with the lower total that you can keep paying every month.
Varidi vs. Scratchpay FAQ
Is Varidi cheaper than Scratchpay?
It depends on the Scratchpay rate you are offered. On a 12-month plan, a 10% Varidi setup fee costs the same dollars as a Scratchpay loan at about 18% APR. Below that rate Scratchpay is cheaper. Above it, Varidi is. At 0% APR Scratchpay adds nothing to the bill, and Varidi always charges its fee.[4][6]
Does Varidi or Scratchpay check your credit?
Which is better for bad credit, Varidi or Scratchpay?
Does Varidi or Scratchpay charge interest?
Can I use Varidi and Scratchpay at the same clinic?
Only if the clinic has signed up with both, since each one works only at participating providers. If it has, check your Scratchpay rate first, because looking does not affect your credit score, and then compare it with the Varidi fee in dollars.
More guides
- Is Varidi really 0%? The setup fee, explained with real numbers
- Varidi vs. CareCredit: which is safer for a vet or dental bill?
- How to pay a vet bill you can’t afford: 8 options, ranked by cost and risk
- No-credit-check dental payment plans: how they work and what they cost
- Varidi requirements: who qualifies and what you need to apply
- Varidi vs. Cherry vs. Sunbit: which payment plan costs less?
- Missed a Varidi payment? What happens and what to do
- Varidi financing: the complete overview
Sources for this comparison (7)
- Humane World for Animals, “Help paying vet bills: Payment plans, resources and more”. Accessed November 12, 2026.
- Varidi, “For Customers”. Accessed November 13, 2026.
- Varidi, “Services”. Accessed November 13, 2026.
- Varidi, “Individual Frequently Asked Questions”. Accessed November 13, 2026.
- Cammisa H.J., Hill S. (2025). “A prospective observational study of how veterinary clinics and their clients utilized a no-credit-check, third-party managed installment financing option to increase access to veterinary care.” Frontiers in Veterinary Science, vol. 12. Accessed November 13, 2026.
- Scratchpay, “How It Works”. Accessed November 12, 2026.
- Scratchpay, “Veterinary” practice page. Accessed November 12, 2026.